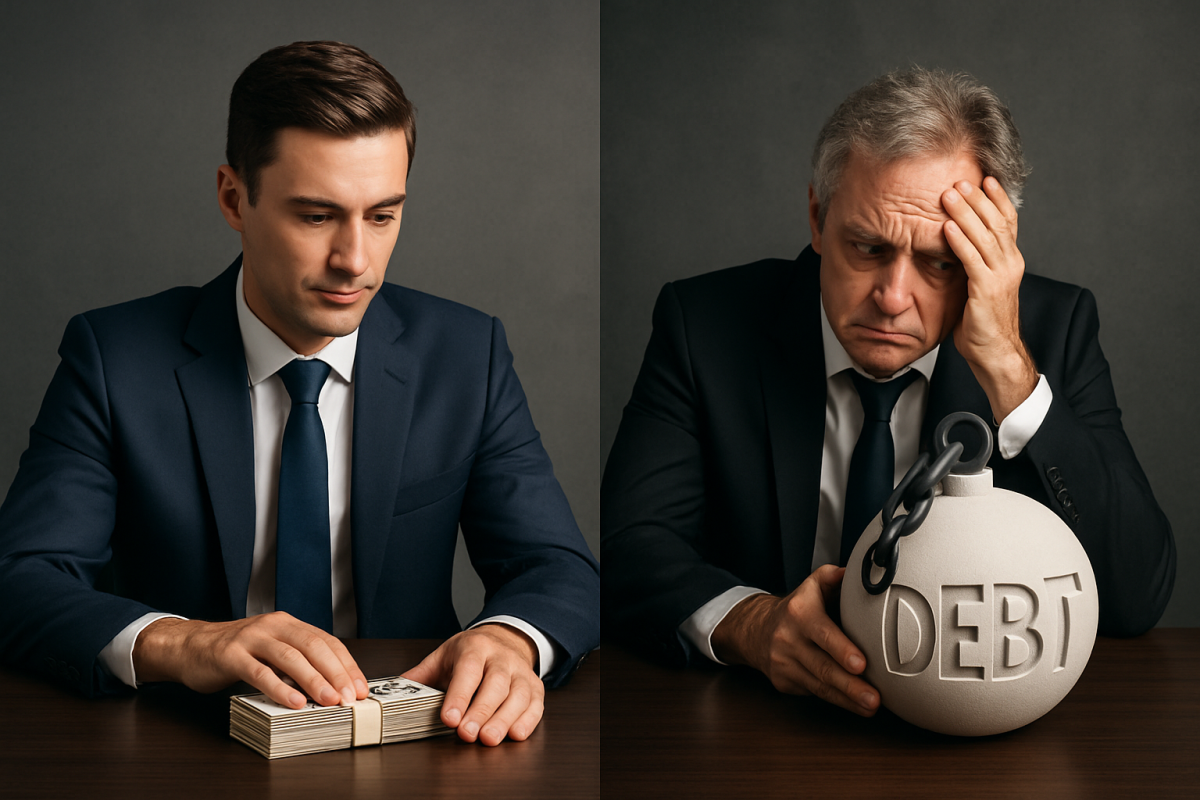
Strategic debt can help a solid business grow. Desperation debt just delays the truth. Learn how to tell the difference before you borrow.
In this series, we have called cash-flow borrowing what it usually is: a Code Red. That does not mean debt is always bad. It means debt has to earn its keep. If the business is healthy, debt can help it move faster, buy equipment, fund a project, or bridge a temporary timing gap. If the business is unhealthy, debt just gives the problem a haircut and a nicer suit.
That distinction matters more than ever for U.S. business owners trying to make decisions in a noisy, advice-heavy environment. Right now, every corner of the internet has a finance guru promising that leverage is the answer. Fine. Sometimes it is. But only when the business model is already sound, the repayment plan is real, and the owner can explain exactly how the debt creates value. Otherwise, you are not financing growth. You are renting denial.
Money does not fix STUPID! It can postpone the consequences, disguise the symptoms, and make the spreadsheet look less ugly for a while. It cannot turn a weak model into a strong one.
Strategic debt versus desperate debt
Strategic debt is deliberate. It has a business purpose, a defined payoff, and a repayment source that exists before the loan closes. Desperate debt is emotional. It is driven by fear, embarrassment, pressure from vendors, or the hope that one more infusion of cash will somehow make the numbers behave.
Here is the simplest test I know:
- Strategic debt funds something with a measurable return or a clear operational improvement.
- Desperate debt funds survival because the business is already short on cash from normal operations.
If your answer to “What will this loan fix?” is “cash flow,” then the business is waving a red flag. A loan should not be asked to do the job of operations, collections, pricing, staffing, or management discipline. That is not borrowing. That is outsourcing responsibility to a lender.
What strategic debt looks like in the real world
Strategic debt is not a fantasy. It shows up in ordinary businesses every week. A manufacturer borrows to buy a machine that reduces labor cost and increases throughput. A contractor takes a line of credit to cover materials on a larger project with a clear invoice schedule. A retailer finances inventory for a seasonal cycle because the margin and sell-through history justify it. A service firm borrows to expand into a new location after proving the first location can throw off enough cash to support the expansion.
In each case, the debt is tied to a working engine. The business already knows how to make money. The loan is there to accelerate, not rescue.
Use this three-question test
- Does the business already generate operating cash? If not, stop. Debt is not the cure.
- Will the borrowed money create a measurable return or solve a defined problem? If the answer is vague, the loan is probably vague too.
- Can the business still repay the debt if the upside arrives later than planned? If the whole plan relies on perfect execution, the plan is fragile.
If those three questions do not hold up, you are not looking at strategic debt. You are looking at wishful borrowing with interest attached.
What desperate debt looks like, and why owners fool themselves
Desperate debt usually arrives in a suit. It sounds professional. It sounds temporary. It sounds like a bridge. That is why so many owners agree to it. They tell themselves they just need a little breathing room, a short runway, a one-time fix, a temporary patch. Then the business asks for another patch. And another.
The common signs are easy to spot if you are willing to be honest:
- The loan is meant to cover payroll, rent, taxes, or overdue vendors.
- The repayment plan depends on sales improving without any operational change.
- The business is using credit to keep up with slow-paying customers.
- The owner expects “a big month” to solve a structural cash problem.
- There is no clear reason the next 12 months will be materially different from the last 12 months.
That last one is the killer. If nothing changes, why would the result change? Hoping harder is not a strategy. It is just stress with better branding.
How to judge whether debt is supporting a healthy model
Before borrowing, look at the model, not the mood. Owners often ask, “Can I afford the payment?” That is the wrong first question. The better question is, “Does the business model produce enough surplus cash to support the obligation after normal operations are paid for?”
Use this simple framework:
1. Start with operating cash flow
Look at cash from normal business activity, not just the bank balance. Are customers paying on time? Are margins real, or are they being inflated by delayed bills? Is inventory moving? Is labor productive? If operations do not reliably produce cash, a loan is just a temporary mask.
2. Identify the debt’s job
Every dollar borrowed should have a job description. If the debt is for equipment, what will that equipment produce? If it is for expansion, what will that expansion change in revenue, margin, or efficiency? If the debt cannot be linked to a specific economic outcome, do not borrow yet.
3. Stress test the repayment
Ask what happens if sales come in 15 percent lower than forecast. What if a key customer pays late? What if the new hire does not work out? Strategic debt survives imperfect conditions. Desperate debt collapses the first time reality shows up without an appointment.
4. Compare the cost of debt to the cost of delay
Some debt makes sense because delaying the investment would cost more than the financing. But be careful. Delay only has a cost when the underlying decision is already sound. Borrowing to cover a bad decision only makes the mistake more expensive.
A practical example: same loan, two very different businesses
Let’s say two owners both want to borrow $150,000.
Owner A runs a profitable service company. The crew is booked, margins are consistent, collections are disciplined, and the company has a history of stable cash generation. Owner A borrows to buy a piece of equipment that cuts job time by 20 percent. The repayment plan is based on actual historical cash flow and confirmed project volume. That is strategic debt.
Owner B runs a similar company, but collections are a mess, pricing is soft, overhead has crept up, and payroll is covered by recurring short-term borrowing. Owner B borrows the same amount to “smooth out” cash. Nothing in the operating model changes. The loan buys six more months of pretending. That is desperate debt.
Same lender. Same paper. Completely different reality. The difference is not the loan product. The difference is whether the business works.
Questions every owner should answer before borrowing
If you want to avoid expensive self-deception, sit down with your numbers and answer these questions in writing:
- What exact problem is this debt solving?
- Is the problem operational, or is it just a timing issue?
- What changed in the business that makes borrowing reasonable now?
- What new cash will this debt create, save, or release?
- What happens if the expected benefit arrives late?
- What happens if the business cannot access more debt later?
- Will this borrowing make the company more valuable, or just more fragile?
If you cannot answer those in plain language, do not let a lender answer them for you. Lenders are not in the business of improving your management. They are in the business of getting repaid.
How to tell whether you are funding growth or feeding a leak
One of the most dangerous habits in business is confusing activity with progress. Owners get busy, spend money, and assume something useful must be happening. Not always. Sometimes the business is just running faster in the wrong direction.
Use this quick filter:
Borrowing may be strategic if:
- The business already has consistent margins and collections.
- The debt funds a specific asset, project, or expansion with a clear payoff.
- The repayment is covered by proven cash generation, not hopes and prayers.
- Leadership can explain the plan without hand waving.
Borrowing is probably desperate if:
- The loan will be used to pay old bills or patch payroll.
- The business needs debt because it cannot convert sales into cash fast enough.
- There is no meaningful operational change behind the borrowing.
- The owner says, “We just need time.” Time for what, exactly?
That question matters. Time is not a business strategy. Time is what you buy when you already have a plan. Without a plan, time just gives the problem more room to grow teeth.
Implementation steps for the next 30 days
If you are considering debt right now, do not rush. Get disciplined. Here is a practical sequence:
- Map your cash flow. Track when money actually comes in and when it leaves. Use real timing, not wishful accounting.
- Separate operating problems from growth opportunities. A growth loan should not be used to cover operational chaos.
- Review your pricing, collections, and margins. These are often the real culprits behind “cash flow” stress.
- Write down the debt’s job. One paragraph, plain English, no buzzwords.
- Build a downside case. If the good scenario fails, can the company still survive the payment?
- Ask one outsider to challenge your logic. Not a cheerleader. Someone who will tell you when the plan smells funny.
That last step is underrated. Business owners can become excellent at defending what they already want to do. A skeptical outside voice can save you from your own enthusiasm, which is often the most expensive emotion in the building.
Debt should reward a strong model, not disguise a weak one. If you borrow before you fix the leak, you are just paying to keep the bucket.
What this means for owners who want to grow or sell later
Strategic debt also affects the future value of the company. Buyers do not fall in love with chaos. They pay for clarity, consistency, and systems that work without heroic effort. If your borrowing history is a trail of emergency fixes, that history matters. It tells the next buyer that the business needed life support, not leverage.
That does not mean debt is taboo. It means debt should make the company cleaner, stronger, and easier to understand. Borrowing that improves operating performance can help a sale later. Borrowing that patches recurring cash problems often lowers confidence and valuation. Buyers can smell desperation. So can lenders. So can your team, eventually.
And if you are thinking about an exit two years from now, this matters even more. Strategic debt taken with clear repayment and a healthy model can be part of a smart transition. Desperate debt, on the other hand, is the kind of last-minute luggage nobody wants to carry.
Bottom line
Do not ask whether debt is good or bad in the abstract. Ask whether the business is already working. If the operating model is healthy, strategic debt can be a useful tool. If the business needs borrowing to survive basic cash flow, that is not strategy. That is a Code Red.
The goal is not to avoid all debt. The goal is to avoid pretending that debt can do the work of management. Build a business that generates cash. Then use debt, if needed, to support that strength. Anything else is just expensive procrastination.
Strategic debt versus desperate debt is not a subtle distinction. It is the difference between investing in a working machine and pouring fuel into one that is already smoking.
Part 4 of 5 in this series.
#Business #Growth #Leadership #tx
Credit: This article was originally published by purpleturtlecapital.com. View the original source
Related posts
The Cash Discipline Reset Your Business Actually Needs