If you need a loan to make payroll, that is not a financing strategy, that is a flashing Code Red that says the engine is smoking and the dashboard lights are trying to quit.
If you need a loan to make payroll, that is not a financing strategy, that is a flashing Code Red that says the engine is smoking and the dashboard lights are trying to quit. A lot of owners still behave as if debt is a magical bridge between today’s mess and tomorrow’s rescue. It is not. It is usually a bill for avoiding the real work.
Part 4 of this series is about the operational reset. Not the motivational speech. Not the lender pitch deck. The actual work: controls, reporting, pricing discipline, and owner decision-making. If you want to fix cash flow without debt, you need to stop treating cash as a mystery and start treating it like the result of a system.
Here is the uncomfortable truth, Money does not fix STUPID! If the business is leaking through weak controls, bad pricing, slow collections, or impulsive owner decisions, a loan just pours more water into the same cracked bucket. You do not solve a hole by adding more bucket.
Debt can buy time. It cannot buy discipline. And discipline is what cash flow usually needs.
Start with the right diagnosis, not the nicest story
Owners love a story that sounds temporary. Seasonal dip. One big customer delayed payment. Payroll timing. A supplier squeezed us. Sure, those things happen. But if the business keeps needing rescue funding, the problem is not one event. It is a pattern.
Before you change anything, answer three questions:
- Where exactly is cash getting stuck?
- Which decisions keep repeating the same problem?
- What would change if every exception disappeared for 30 days?
This is not a philosophical exercise. It is a practical one. When you know the pattern, you can build the fix. When you do not, you just keep rotating chairs on the Titanic and calling it management.
Reset control number one: the 13-week cash view
If you are flying blind, stop pretending you are in control. A 13-week cash view is not fancy, it is basic survival. It shows what cash is expected to come in, what is due to go out, and where the pressure is building before the panic starts.
Do not ask your bookkeeper for a masterpiece. Ask for a simple, honest view with three lines:
- Cash coming in, by week.
- Cash going out, by week.
- Known gaps or shortfalls, by week.
Then review it every week, not when someone remembers to ask. If your business cannot forecast cash for the next 13 weeks with reasonable accuracy, that is a management problem. Full stop.
Practical implementation:
- Use actual collections history, not wishful invoicing.
- List every payroll, rent, tax, debt, and supplier payment due.
- Mark anything uncertain in a separate column.
- Update it every Friday.
The point is not perfection. The point is visibility. Cash flow gets dangerous when surprises become normal.
Reset control number two: collections and receivables discipline
Many businesses do not have a cash flow problem, they have a collection problem wearing a fake mustache. They did the work, issued the invoice, and then behaved as if the customer’s payment schedule was their schedule. That is how owners end up borrowing money for money they have technically already earned.
Fix the collection chain:
- Invoice immediately when the work is done.
- Make terms explicit before the work starts.
- Follow up on day one after the due date, not day thirty-three when the damage is already baked in.
- Escalate repeat offenders.
If a customer pays late every month, that is not a harmless habit. That is a financing relationship you did not agree to. And if you keep funding that customer with your own cash, congratulations, you are now their bank, with worse underwriting.
Track these numbers weekly:
- Accounts receivable over 30 days
- Accounts receivable over 60 days
- Disputed invoices
- Concentration by customer
If one customer dominates your receivables, your business is more fragile than the owner thinks. One slow payer should not be able to send the whole company into a cash panic.
Reset control number three: spending discipline with adult supervision
When cash is tight, most businesses do not need more ideas, they need fewer impulse purchases. That means the owner has to stop approving every shiny thing that lands in the inbox.
Here is the rule: every expense must earn its place. If you cannot explain how a cost improves cash, margin, speed, or risk, it gets delayed or cut.
Start with a spending freeze on non-essential items for 30 days. Not forever. Thirty days. That is long enough to reveal what the business actually needs versus what it merely enjoys spending on.
Review these categories first:
- Travel and entertainment
- Software subscriptions no one uses
- Consulting and ad hoc outside services
- Replacement hires that were never fully justified
- Owner perks disguised as business necessities
You are not being cheap. You are being responsible. There is a difference, and lenders know it.
Reset control number four: pricing discipline
A lot of owners want to fix cash flow without touching pricing because pricing is emotionally annoying. They fear losing customers, annoying salespeople, or admitting they underpriced the work for too long. But underpricing is just silent self-harm with better branding.
If margins are weak, cash will always feel tight. You can collect faster, trim expenses, and still be trapped if your pricing cannot support the operating model.
Run this test:
- Identify your top 10 products, services, or job types.
- Calculate gross margin on each one.
- Highlight the ones that create volume but destroy cash.
- Ask whether you should raise price, change scope, or stop selling them.
Sometimes the issue is not that you need more revenue. It is that you need better revenue. Bad revenue is busy, flattering, and cash-poor. It looks productive until payroll arrives.
If your team argues that the market will not support a price increase, ask them what part of the current model is worth preserving. A business that cannot charge enough to fund itself is not stable. It is just occupied.
Reset control number five: owner decision-making
This is the one people hate because it cannot be outsourced. A broken cash flow cycle often survives because the owner keeps making the same reactive decisions under pressure.
Common owner mistakes include:
- Approving discounts without understanding margin impact
- Buying inventory before demand is proven
- Hiring ahead of cash capacity
- Delaying hard conversations with poor customers or poor performers
- Confusing urgency with importance
Ownership means deciding what not to do. That is where the real work happens. Purpose is not a poster on the wall. It is a decision you keep making.
Try this: before approving any major spend, ask three questions:
- Does this help us collect cash faster?
- Does this improve margin or reduce waste?
- What happens if we wait 30 days?
If the answer is vague, the answer is usually no.
A practical 30-day operational reset
Here is a simple reset plan you can run without borrowing your way into deeper trouble.
Week 1: See the problem clearly
- Create a 13-week cash view.
- List overdue receivables by customer.
- Freeze non-essential spending.
- Review the last 90 days of cash outflows.
Week 2: Tighten collections and approvals
- Call every overdue account.
- Change invoice timing if work is being billed too late.
- Require approval for discounts and spend exceptions.
- Stop silent leakages like untracked reimbursements or casual purchases.
Week 3: Attack weak margins
- Review pricing on your lowest-margin offers.
- Identify customers or jobs that consume too much time for too little return.
- Adjust scope, pricing, or terms.
- Drop the work that looks busy but behaves like a cash vacuum.
Week 4: Make the owner role stricter
- Set a weekly cash review meeting.
- Assign one person to update the forecast.
- Build a rule for exceptions.
- Document what gets approved, what gets delayed, and what gets rejected.
This is not glamorous. Good. Glamour is how people end up explaining cash crises to their spouse on a Sunday night.
What strong operators do differently
In my experience, the businesses that recover cash flow without emergency borrowing are not the loudest. They are the clearest. They know what they sell, what it costs, how quickly customers pay, and which decisions belong to the owner.
Weak operators ask, “Where can we get funding?” Strong operators ask, “Where is the system broken?” That second question is harder, but it produces actual answers.
The best owners I have seen do three things consistently:
- They face numbers early.
- They cut emotional spending before the market forces it.
- They refuse to confuse activity with progress.
That is how you build a business that generates cash instead of periodically begging for it.
Use the reset to protect the business, not the ego
This is where some owners get tripped up. They think tighter controls are a sign of weakness or failure. It is the opposite. Controls are what adults build when they stop hoping the next month will magically be different.
A low valuation from a buyer is not a directed insult to you personally, it just shows what is valued by those on the outside, Use this knowledge for the better. The same logic applies here. If your cash flow is fragile, the numbers are telling you what outside reality already sees. Listen before it costs you more.
You do not have to like the diagnosis. You do have to use it.
Checklist: signs your cash flow reset is working
- Receivables are getting collected faster.
- Weekly cash forecasting is accurate enough to guide decisions.
- Spending approvals are fewer and more deliberate.
- Pricing is aligned with margin, not hope.
- The owner is making fewer reactive decisions.
- The business is less dependent on borrowed cash to function.
If those items are moving in the right direction, the business is getting healthier. If nothing changes except the lender conversation, you are still treating symptoms.
And yes, this is also why exit planning matters. A business that cannot generate clean cash today is not in great shape to sell tomorrow. The sooner you install discipline, the less ugly the cleanup later. Better to gift wrap a strong company than to arrive at the sale table with a box full of excuses.
In part 5, we will close the loop on what to do when the model itself needs a deeper rebuild. For now, the assignment is simple: stop reaching for money as the first answer, and start acting like an owner who expects the business to earn its own survival.
Use this week to run the reset, not the rescue fantasy. Fix the controls. Tighten the pricing. Clean up the approvals. Then watch what happens when the business is forced to tell the truth.
Part 4 of 5 in this series.
#Business #Growth #Leadership #tx
Credit: This article was originally published by purpleturtlecapital.com. View the original source
Related posts:
 When Cash Flow Needs a Loan, the Business Model Is Already Shouting
 Strategic Debt vs Desperate Debt: How to Tell Whether Borrowing Is Building or Breaking You
 Debt Is a Tool, Not a Bandage: How to Decide If Borrowing Is Strategic or Panic
 Money Does Not Fix S*%$d!!! Why Borrowing Cannot Repair Bad Operations
Related posts
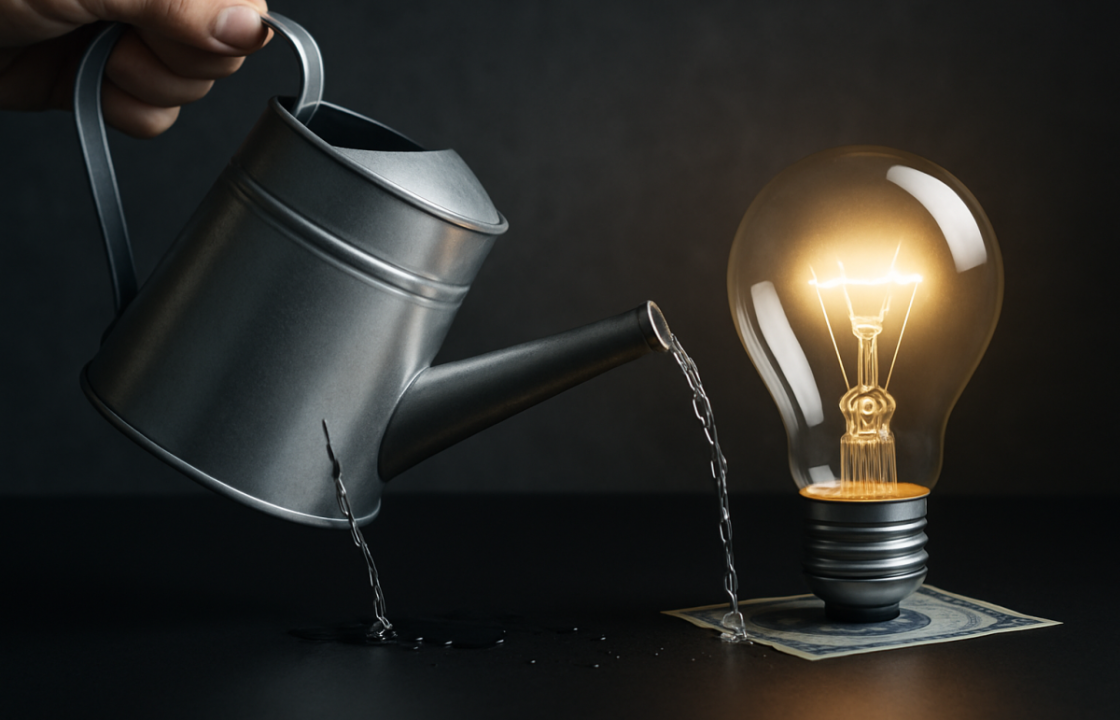
If You Need Cash to Keep the Lights On, Find the Leak Before You Pour More In